Solar AD/CVD forecasts need separate current and future deposit rates
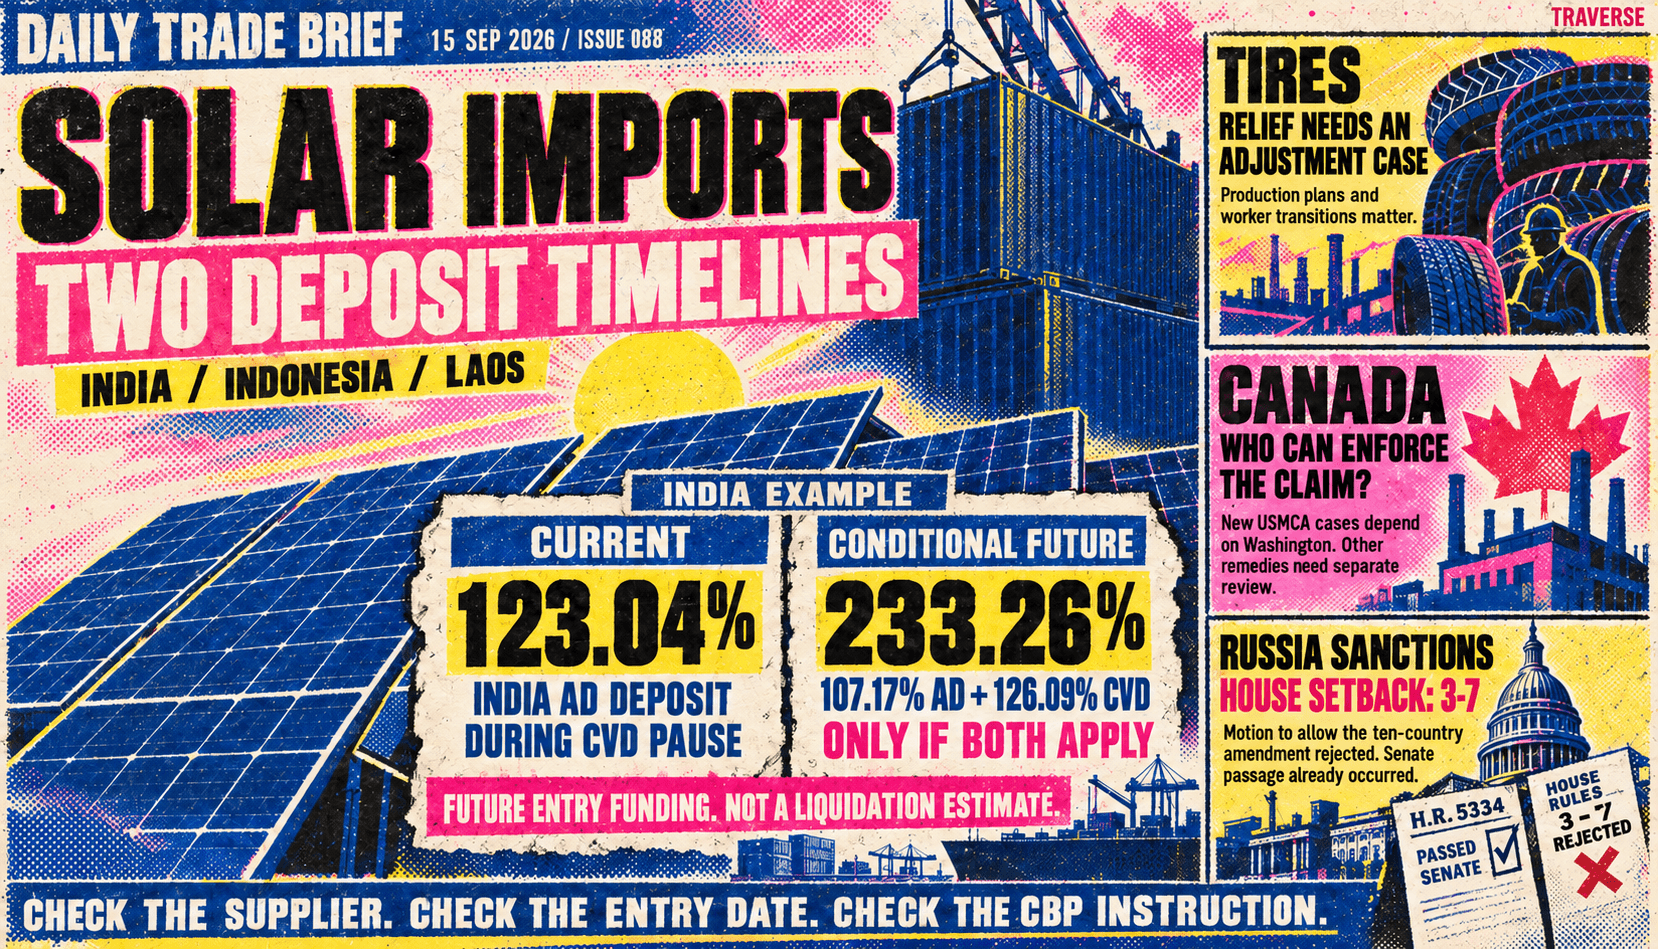
Match each solar shipment to its supplier, entry date, and applicable CBP instruction. Budget separately for deposits on current entries and conditional increases on later entries if CVD collection resumes.
Solar importers need to distinguish the cash due on today's entries from the financing a later shipment may require. Yesterday's analyses also examine tire-industry restructuring, investment remedies in Canada, and a proposed Russia sanctions tariff list whose House path has since narrowed.
Solar: Separate current deposits from future funding. Announced AD/CVD totals for India, Indonesia, and Laos do not establish the cash due on every shipment. India's AD deposit instruction specifies 123.04% during the CVD pause. The announced 107.17% adjusted AD component plus 126.09% CVD would total 233.26% if both later apply. That difference is a future entry-financing scenario, not a forecast of additional liability on existing entries at liquidation. Model each supplier and entry date separately. The CVD instructions tie resumption to Federal Register publication of an affirmative ITC final determination.
Read the full analysis: Solar AD/CVD Totals Can Misstate the Cash Due at Entry.
Tires: Explain what safeguard relief would change. Section 201 allows positive adjustment even if the domestic industry becomes smaller or reorganizes, but displaced workers must also make an orderly transition to productive pursuits. Production transfers and worker arrangements therefore matter to the case for a remedy. They do not replace the separate requirements concerning increased imports, serious injury or its threat, and causation. Counsel should distinguish restructuring already planned from changes the requested relief would support. A safeguard request creates no new duty.